All Categories
Featured
Comparing Whole Life Insurance Premiums
You may not need a life insurance coverage policy after you have actually paid off your debts and saved for your huge monetary goals, like retirement and your kid's college education. In these situations, a term life insurance policy with a separate retirement fund and other cost savings vehicles might use what you need, and at a lower cost tag. Once you have a few quotes, you need to: Compare protection limits, approximated monthly payments and administrative or management fees that come with each policy.
Instead, the insurance business uses the index as a benchmark to figure out how much interest to credit to the money worth part of your policy. If the index has a bad year, your credited interest may be lower(sometimes even 0%), depending on your policy's terms. If your policy credits the.
full 10%, your cash value could earn about Make5,000 in interest before fees and costs charges.
Expect your policy has a 10 %cap, and the market index gains 15%that year. Despite the fact that the index increased by 15 %, your policy would just be credited 10 % before fees and other policy charges. Numerous IUL policies have a 0 %floor, indicating you won't lose cash value just because the underlying market index has a negative year. If the index falls 18%, your credited interest may be 0%rather of -18%. That said, a 0 %floor secures you from market losses, not from policy costs. An involvement rate identifieshow much of the index's gain is credited to your policy. For example, if your policy has an 80 %involvement rate and the index increases 10%, you would get 8%interest (80%of the index's gain), presuming no cap restricts the return. If the participation rate is 100 %, you would make the complete 10 %as long as it doesn't surpass the cap. 2 policies tracking the same marketindex can produce extremely various outcomes depending upon how these features are structured. The majority of indexed universal life policies let you pick between 2 kinds of death benefits: Your beneficiaries get a fixed survivor benefit throughout the life of the policy. As your cash value grows, it normally becomes part of that total survivor benefit instead of being paid in addition to it.
The Comprehensive Guide on 2026 Medicare Options
That versatility can be huge if your earnings modifications from year to year, or you go through a big life occasion (such as divorce or short-term work leave) and still wish to keep your policy in force. However it likewise means you'll require to pay closer attention to your policy gradually.
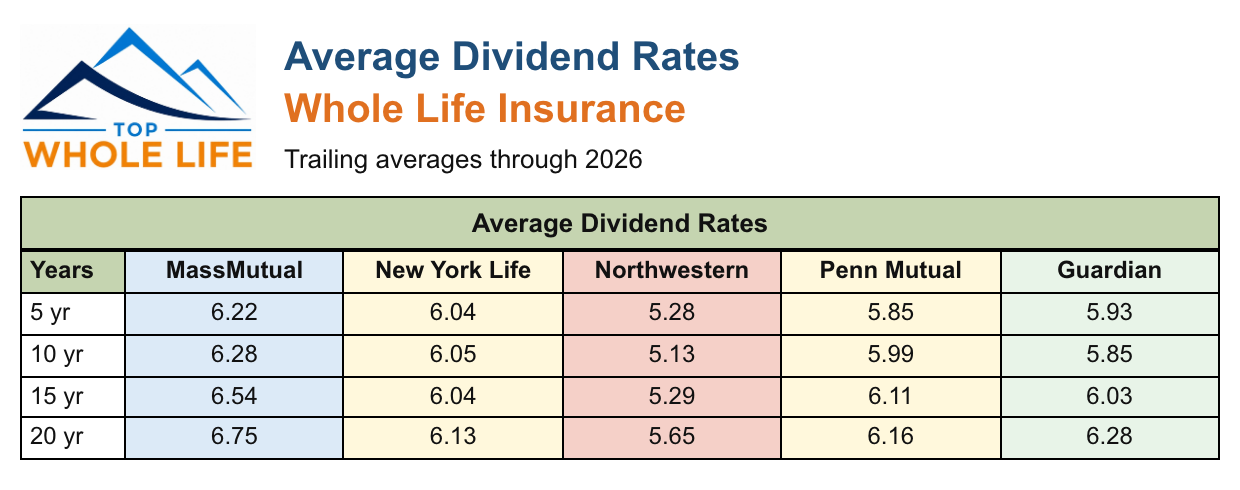
Insurance in Colton CAThis table highlights the most significant differences: Both entire life insurance coverage and indexed universal life provide you with irreversible protection that builds cash worth, however how that cash worth grows is rather different. Entire life insurance normally has actually ensured growth at a set rate, while IUL has the potential for greater returns since its money worth is tied to a market index.
Term life insurance coverage is typically the most budget friendly and easiest kind of life insurance to get. It doesn't build cash worth, but you get a guaranteed death benefit for a set period of time, frequently at a fraction of the cost of an IUL policy. You can consider a variable universal life insurance policy as one step above an IUL policy in terms of risk and reward.
Insurance in Colton CAThis implies you'll have higher growth potential however also the possibility of financial investment losses. Like any financial product, indexed universal life insurance has advantages and trade-offs. If your main objective is just replacing your earnings for your family, a term life insurance coverage policy is usually simpler and far cheaper.
Common expenses may include:, which typically increases as you age for handling the policy deducted from your payments if you add features like long-term care or persistent illness benefits if you cancel the policy throughout its early years Before you buy an indexed universal life policy, the insurance coverage business will usually offer an illustration demonstrating how your policy might carry out in time.

Latest Posts

How Whole Life Insurance Provides Security
Finding Affordable Family Health Insurance in 2026
Comparing Whole Life Insurance Premiums